What Hungary's Top Bankers Are Saying About the Economy Right Now
The Financial Conditions of the Fast Lane: Who Is Funding Hungary's Growth?
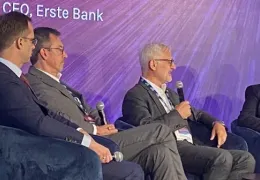
26th HBLF Financial Summit, CEO panel with Krisztina Bogdán (ING Bank), Radován Jelasity (Erste Bank), Peter Roebben (K&H Bank) and Richárd Végh (KAVOSZ), moderated by András Bácsfalvi.

KEY MESSAGE
Hungary does not need more money. It needs more productive investment. Liquidity is abundant and banks are ready to lend. What holds companies back is a lack of confidence, predictability and a clear economic narrative. New government initiatives are improving sentiment, but confidence has not yet fully returned.
1. MONEY IS NOT THE BOTTLENECK
Excess liquidity. Companies are net depositors. Banks hold large sums at the central bank and in government securities, and the loan-to-deposit ratio is low.
Weak investment. Over the past two to three years, Hungarian companies invested less than their depreciation.
Cautious management. High interest rates, geopolitical tension and supply-chain disruption have made companies reluctant to commit capital.
2. PREDICTABILITY MATTERS MORE THAN CHEAP CREDIT
Predictability is the priority. Companies need stability in the economy, in government policy and in access to financing.
Clarity helps planning. Clear communication, including whether subsidized schemes will continue, is better than uncertainty.
Cheaper credit alone would not help. Companies invest when they see a path to adequate returns and have the confidence to take risk.
Cheap money has side effects. About 30–35% of business lending is subsidized, which weakens the incentive to improve competitiveness. Hungarian productivity is around 70% of the EU average.
3. RETHINKING STATE-SUPPORTED LENDING
Stop-and-go cycles. Subsidized schemes have dominated bank product development, and lending has followed program announcements rather than market demand.
Justified in the crisis. Support was necessary during the period of record-high interest rates, especially for companies without export income.
Normalization is under way. The subsidized share should decline gradually, though not to zero. The transition must be managed carefully, as around 80,000 SMEs, mostly micro-enterprises, rely on these products.
Principles for future programs. Additionality, clear targeting, and broad support reserved for crisis liquidity.
A proposed trade-off. Phase out subsidized lending in exchange for removing the extra taxes on banks.
Market-based SME loans are still costly. Hungary has the second most expensive in the EU.
4. DEEPENING THE FINANCING ECOSYSTEM
Credit culture. Borrowing is still often seen as a risk rather than a tool for growth. At around 25–30%, credit-to-GDP is among the lowest in the region, and many SMEs cannot scale or become exporters without it.
Capital markets and equity. Alongside a developing stock exchange, a stronger venture capital and equity ecosystem would help innovative startups grow faster.
Foreign interest. Investor interest is markedly stronger than in recent years, raising the likelihood of M&A activity. Companies need better governance and transparency to benefit.
5. WHAT MAKES A COMPANY WORTH FINANCING
The fundamentals. A long-term vision and a solid business plan with a clear path to value creation.
Leadership. A strong management team and a credible track record. The final decision rests on trust and judgment that credit models cannot fully capture.
Warning signs. Borrowing because a subsidized scheme exists, or moving into unrelated sectors such as property development.
Focus on the core business. Growth works best where a company already has expertise.
Succession planning. Family businesses in the region are going through their first generational handover, a high-risk transition that needs early preparation.
WHAT WILL PUT HUNGARY BACK IN THE FAST LANE?
Investment gains momentum. New projects draw in further investment, supported by access to global expertise and funding.
Pending funding is unlocked. EU funds in particular are essential for growth, fiscal discipline and eventual euro adoption.
Productivity catches up. The data shows Hungary on track to reach 80–90% of average EU productivity by 2030.